
M&G: Why Europe’s impact funding gap calls for private credit
M&G: Why Europe’s impact funding gap calls for private credit
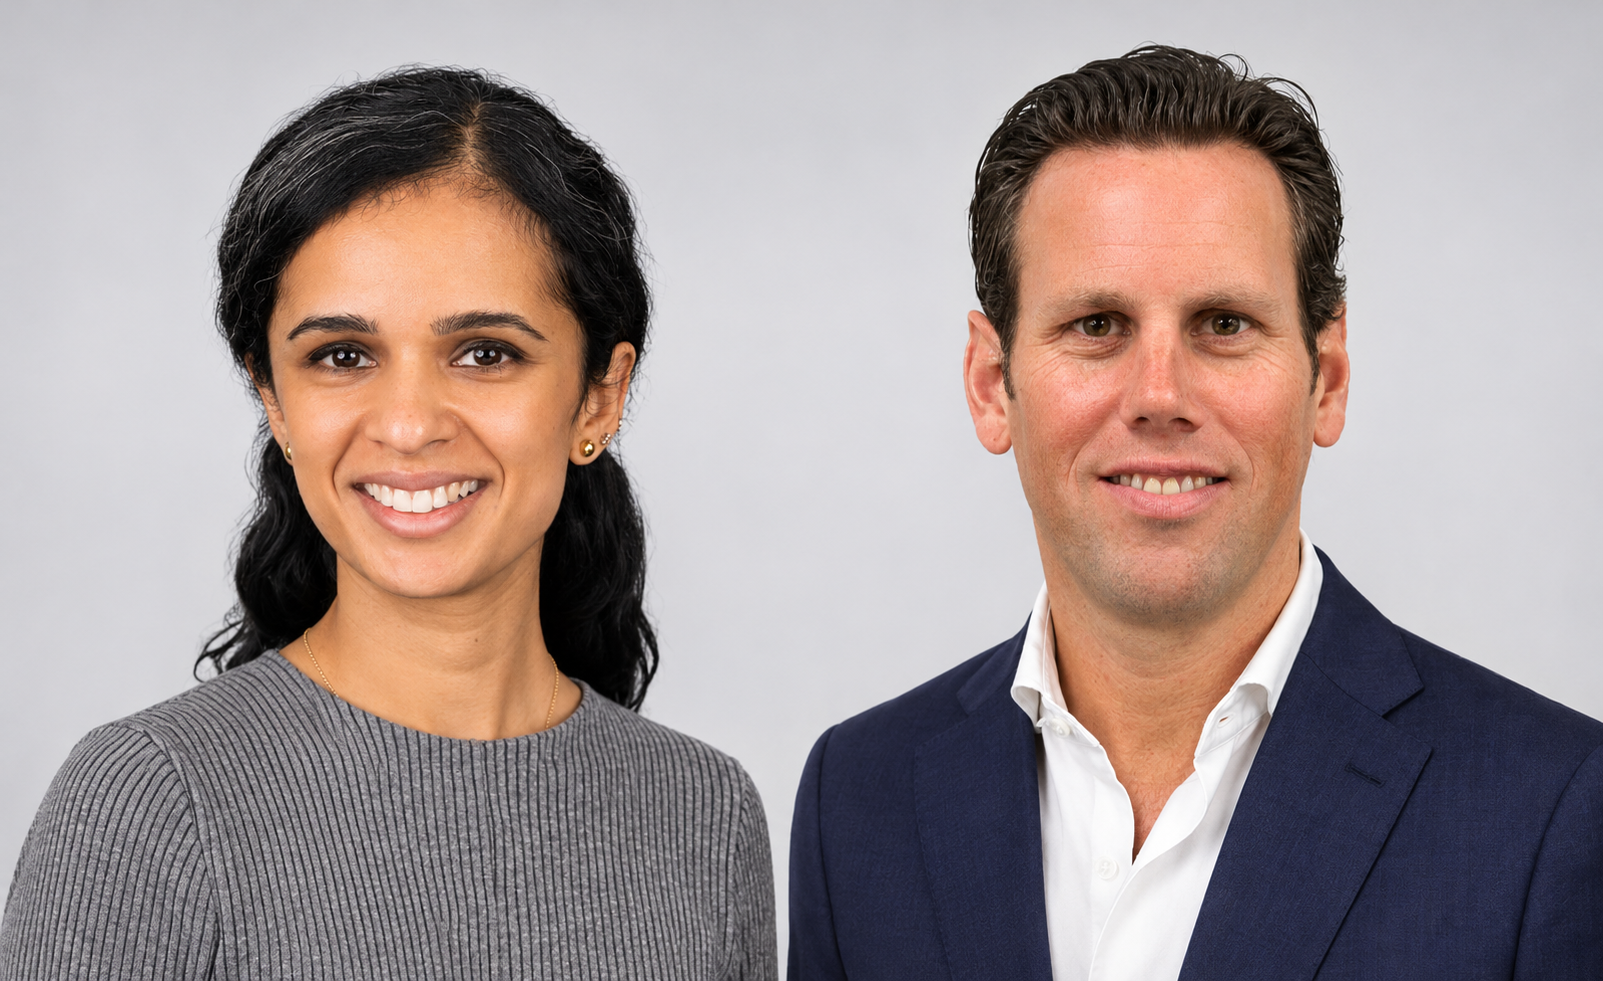
Europe needs private capital to address climate, healthcare and inequality challenges. While private equity has traditionally dominated impact allocations, impact private credit is increasingly in the spotlight. Financial Investigator spoke with Aditi Rao and Gijs Boumans of M&G Investments about its potential to help close Europe’s impact funding gap while delivering attractive risk-adjusted returns.
By Michiel Pekelharing
Why does private credit belong in an impact allocation?
Aditi Rao: ‘When people talk about impact investing in private markets, they are almost always referring to private equity. While great things are happening in that segment, credit has its own role in scaling up impactful companies, given that debt has a lower cost of capital than equity. We have very good relationships with our borrowers and can engage meaningfully with companies in our portfolio in a variety of ways. Nevertheless, institutional players that direct their portfolios towards impact allocate significantly more to private equity than to private credit. It takes time to dispel the misconception that impact investing in private credit necessarily means accepting lower returns or having less influence. Moreover, in Europe there is a large funding gap for impactful solutions, so there is a huge opportunity for debt capital to help address it.’
Can you explain this opportunity more?
Rao: ‘Europe has great ambitions but is also facing great challenges. Just think of decades of underinvestment in infrastructure, among other things. Europe is the fastest warming continent in the world and has an ageing population that is increasing the pressure on public services. Governments cannot solve the problems entirely on their own, and private capital has an important complementary role to play. At the moment, only a small part of that capital comes from impact private credit. Those who see this as an opportunity will discover a series of interesting themes in which to invest. Our strategy focuses on developed markets in Europe, along the themes of climate and nature, healthcare and social equality.’
Gijs Boumans: ‘Historically, European companies were mainly financed by banks, but the shift to private credit has been going on for more than ten years. I have fifteen years of experience in leveraged finance at ABN AMRO. Two years ago, I decided to join M&G because I saw the market evolving and wanted to be part of the growth of private credit. What appeals to me is the closer interaction with sponsors and management teams, the flexibility to tailor financing solutions, and the speed with which decisions can often be made. Many entrepreneurs and private equity investors value having a handful of financing partners rather than coordinating a broader banking syndicate. As the gap in pricing between private credit and traditional bank financing has narrowed, the two markets have increasingly converged.’
What is the difference between ethics and a good business case?
Rao: ‘Good intentions do not automatically equate to a good impact investment. Take the circular economy, for example. You can recycle because you’re a good citizen. Or you can acknowledge that we as humanity consume too many finite resources and that regulations should respond to this. There will be increasing limits on what can go to landfill and the linear consumption model cannot last. We will therefore have to reuse or recycle much more than we do now. Companies that apply circular principles have a tailwind for their business model. We are a credit house, so we always look at the risks first. But an investment case becomes more convincing when there is a clear tailwind underneath it. If a significant proportion of the turnover of a circular company is supported by regulations that are already in force, then that protects my downside.’
We don’t just put an impact label on a loan.
How do you distinguish real impact from good intentions?
Rao: ‘Impact is now mainstream, but everyone uses a slightly different definition. That is a hurdle that the sector still has to overcome. We follow the widely accepted frameworks such as Impact Frontiers’ Five Dimensions, but our interpretation sets the bar high. We work with theories of change. We define the problem in advance, as well as the solutions that address it. When the team that originates the loans comes up with a transaction, the question is always which problem the company is providing a solution for, and whether its contribution is material. Take a fictitious example of a sprinkler system that uses 10% less water. That sounds nice, but sprinklers are not even in the top ten freshwater consumers in the EU. Agriculture and industry consume by far the most. Such a sprinkler is therefore not a material solution to the water problem, no matter how sympathetic.’
Boumans: ‘That discipline sometimes creates tension. As an originator, you want to make investments, but M&G is a diligent research house and extremely disciplined when it comes to credit analysis and impact assessment. We don’t just put an impact label on a loan. That’s not always easy when you want to deploy capital, but in the long run it makes all the difference.’
How big is the risk of impact washing?
Rao: ‘That risk cannot be ignored. In the United Kingdom, SDR regulations have now come as a counterpart to SFDR, although the two regimes serve different purposes. SFDR is primarily a disclosure regime, and an Article 9 classification does not automatically mean that a fund is an impact fund. There are also Article 8 funds that pursue impact objectives. SDR introduced the concept of a theory of change, and that makes it much clearer for impact funds. Some funds without clear theories of change see an investment and then wonder how they can turn it into an impact story. We take the opposite approach. The problem and associated solution are predefined.’
Can you achieve impact if this is not a priority for the owner?
Rao: ‘The deals are easier if the equity party also has impact objectives. But we have plenty of examples where that is not the case and where we can still make progress. It requires more involvement and engagement with the company. Recently, we engaged with a portfolio company whose owner is not particularly focused on impact to ask for better KPIs to help with measurability. The CEO was happy to help because he understands that his company benefits from access to impact capital. As we are an important provider of capital, he entered into the conversation and agreed to provide the necessary information.’
Boumans: ‘Companies often have more to offer than they show. If you really ask a financial executive, sometimes a person dedicated to sustainability suddenly joins in. Private equity parties who have to report to their LPs not only appreciate our money, but also our role as a sparring partner who asks challenging questions.’
It is often said that the Dutch market is at the forefront of impact investing. Is that still the case?
Rao: ‘The Dutch market is unique in how impact-oriented it is. Two or three other European countries are coming close, but the Netherlands is far ahead. Regulations help and the level of knowledge in the market is very high. Many Dutch investors understand that impact does not mean that you invest at below-market returns. There is no notion of concessional capital here. Approaches differ elsewhere in Europe, including in Scandinavia, and outside Europe, views on impact are more mixed.’
Good intentions do not automatically equate to a good impact investment.
Boumans: ‘Dutch institutional investors are increasingly looking for long-term partnerships with their asset managers. As the market continues to evolve rapidly, investors recognise that many of the challenges and opportunities, particularly in areas such as impact measurement and biodiversity, are best addressed through close collaboration and shared learning. They value relationships where both parties can exchange knowledge, develop expertise together, and refine approaches over time. This collaborative model also helps address the fact that concepts such as impact can be defined differently across organisations.’
Where do the wishes of investors clash with practice?
Rao: ‘There is always a discussion about the definitions, but our rigorous definition already matches those of our clients. A discussion on themes can take longer because many clients come with a narrower thematic focus, for example only on climate. This can lead to a concentrated portfolio that is more difficult to deploy and will have more idiosyncratic risks, so we work with clients to show them that broadening the lens improves both credit diversification and impact outcomes.’
How do you deal with a late stage in the credit cycle?
Rao: ‘I was a credit analyst for ten years, so credit risks are always on my mind. We are conservative by nature, both on credit and on impact. There are many impact houses that started as impact-first and are still building up credit expertise. Our heritage is exactly the other way around. And if things do go wrong, we have a strong workout and restructuring team.’
Boumans: ‘We have been hearing for five years that rising interest rates can cause problems for borrowers, so we remain cautious not to structure transactions too aggressively. Everything revolves around downside protection, a diversified portfolio that is not overly levered, and historically very low defaults. With every investment, we look five to seven years ahead. If a business plan does not develop as expected, we act as a partner and look at what is really happening in the sector, instead of just focusing on a breach of covenant.’
What does the new Dutch pension system mean for demand?
Boumans: ‘Dutch pension funds have a long horizon and are willing to use it. As funds progress through the pension transition, many are reassessing their investment portfolios. Only half of the funds have gone through the transition. The rest are still focusing on liquidity, but as soon as they take the next step, they will look for higheryielding investments and want to combine that with impact. We are currently experiencing a very active period of client engagement and RFP activity in impact credit.’
Rao: ‘Insurers are also showing increasing interest. For insurance mandates, we take the Solvency Capital Requirement into account. Private credit scores favourably there, and qualifying infrastructure even more so. With credit teams spanning direct lending, infrastructure loans and private placements, we believe we are well positioned to deploy capital. For investors looking beyond developed markets after years of impact investing in Northern Europe, our sister organisation responsAbility also provides access to impact opportunities in emerging markets. But the core focus for us remains Europe, where we continue to see substantial long-term opportunity beyond short-term market noise.’
|
Aditi Rao Aditi Rao has been on the fund management team of M&G’s Impact credit strategy since 2022. Prior to that, she was a Director in the Leveraged Finance team for over 10 years, where she led on mid and large cap LBO transactions, as well as spear-heading ESG research. Rao holds a Master in Sustainability Leadership from the University of Cambridge, where she also studied Natural Sciences as an undergraduate. She is a CFA Charterholder. |
|
Gijs Boumans Gijs Boumans is a Senior Director in M&G Investments’ Private Corporate Credit team, having joined the firm in 2025. Based in Amsterdam, he is responsible for originating and executing mid-market private credit investments across the Benelux region. He also supports the continued development of M&G’s impact investing capabilities. Before joining M&G, Boumans spent 15 years with ABN AMRO, where he held a range of roles across Corporate Banking. |
Read the interview in the digital magazine
Deel dit bericht
Gerelateerde berichten
-
 Lees meer over "Van Lanschot Kempen: Impact in private debt - hoe dichterbij, hoe krachtiger"
Van Lanschot Kempen: Impact in private debt - hoe dichterbij, hoe krachtiger
-
 Lees meer over "Symbiotics: Private debt in opkomende markten is volwassen, schaalbaar en relevant"
Symbiotics: Private debt in opkomende markten is volwassen, schaalbaar en relevant
-
 Lees meer over "DWS: Zorgvastgoed is populair, maar het aanbod is schaars"
DWS: Zorgvastgoed is populair, maar het aanbod is schaars
-
 Lees meer over "Danny Dieleman: Is de NAV van een private credit-fonds de hele, of de halve waarheid?"
Danny Dieleman: Is de NAV van een private credit-fonds de hele, of de halve waarheid?
-
 Lees meer over "Ronde tafel 'Impact Investing in Private Equity'"
Ronde tafel 'Impact Investing in Private Equity'
-
 Lees meer over "Achmea IM en ILX bundelen krachten voor impactbeleggen in opkomende markten"
Achmea IM en ILX bundelen krachten voor impactbeleggen in opkomende markten
-
 Lees meer over "Savills IM: European real estate debt finds its moment"
Savills IM: European real estate debt finds its moment
-
 Lees meer over "Jori Arts: Waarom impactbeleggen de beurs nodig heeft"
Jori Arts: Waarom impactbeleggen de beurs nodig heeft
-
 Lees meer over "Van Lanschot Kempen: 34% deelnemers bereid pensioen in te leveren voor impact"
Van Lanschot Kempen: 34% deelnemers bereid pensioen in te leveren voor impact
-
 Lees meer over "Webinar 'Impact & Green Bonds'"
Webinar 'Impact & Green Bonds'