
Dick Kamp: Where to start with risk management under the Wtp?
Dick Kamp: Where to start with risk management under the Wtp?
This column was originally written in Dutch. This is an English translation.
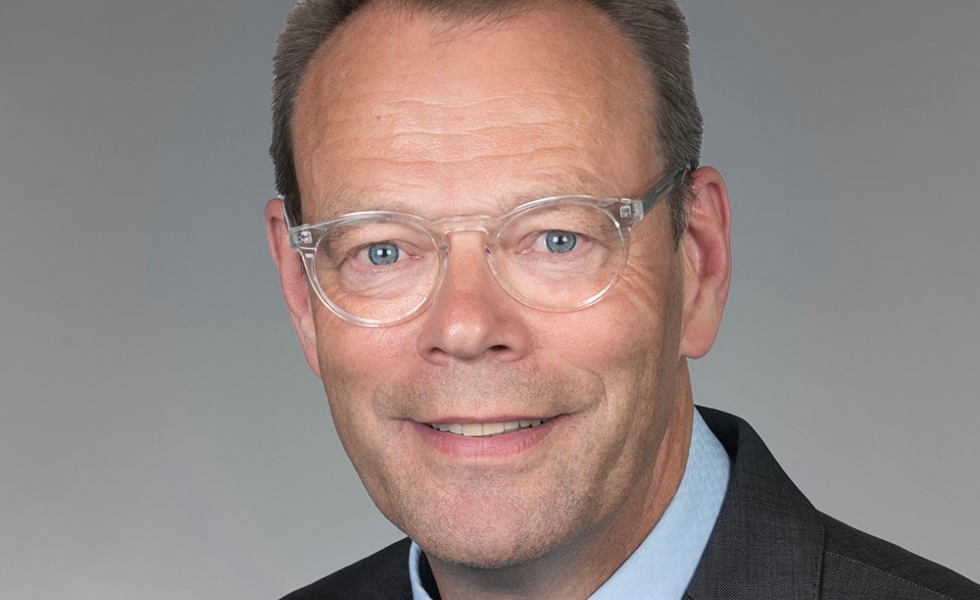
By Dick Kamp, Director of Pension Investment & Risk at Milliman Benelux
Are you a pension fund trustee, and has your fund transitioned to the new Dutch pension system? If so, your board's focus is shifting from transition to oversight and risk management. One question is central: does your monitoring show whether you are actually going to achieve your objectives, and does it provide sufficient guidance to make timely adjustments if it appears that this might not be the case?
I’m sure you’ll recognise this. You’ve settled into the new routine and your mind is clearing again. It’s been such a hectic few years! All our focus was on the transition to the new pension scheme. That was necessary, too, because it was a tough journey. The discussions — internally, with external service providers and, not least, with the regulator — were intense. You could almost forget why this transition matters. So let’s go through it all again. My take on it, that is. There are surely other ways of looking at it, but I think it’s important to set out my view here.
Why we embarked on this journey
The following breakdown is a personal classification, not an exhaustive or official account of the reasons for embarking on this journey. As far as I’m concerned, these were the reasons for switching to the new system:
- Risk of inflation. Keeping pace with (price) inflation — given the available contribution and the restrictions on the investment risk that could be taken — was not (always) manageable under the FTK.
- Scope for personal choice. The collective scheme — with its collective assets — ultimately restricted participants too much in making their own choices across all stages of their lives.
Had these reasons not been adequately addressed in the implementation, they would have continued to haunt us. Public acceptance of our system would then have come under pressure once again — and we could not afford that. The stakes were simply too high:
- (Relative) certainty about income after retirement leads to consumption in the period leading up to it.
- Consumption is a key driver of economic activity and prosperity.
- A pension is saving for later. Those ‘savings’ are invested and finance our country’s economic activity.
- Investment is therefore also a driver of economic activity and prosperity.
From objective to risk management
What does this have to do with risk management? Everything, as far as I’m concerned. After all, the shortest definition of risk management is the control of those risks that hinder the achievement of the objective. Key concepts: objective, risks, control.
The first thing you must do as a director is to reflect on the objective of the organisation you manage — bearing in mind the founding principles. What do these mean for your fund’s mission, vision and derived strategy? Anne Laning addressed a related issue in his opinion piece on PensioenPro (5 October 2026).
I see two paths ahead for you.
Path 1 concerns the implementation of the social partners’ mandate. Much of this has already been set out in the implementation plan. The main priority now is to ensure that the established operational procedures actually work and are optimised in terms of inflation risk and the range of options available. Appropriate monitoring is crucial for this. However, monitoring alone does not constitute control: it must also be clear in advance which outcomes require the board’s attention, who will act on them and how any necessary adjustments will be made.
Path 2 concerns the further development — call it innovation — of your own value proposition: better management of inflation risk and greater scope for participants’ choices, both before and after retirement. This path goes beyond optimisation within the existing frameworks; it is more complex and requires the cooperation of multiple parties. More on this in a follow-up article.
Path 1: monitoring, accountability and optimisation
You know from experience: you tend to tackle what you actually measure. You carry out this measurement via a monitoring dashboard, which is currently the subject of much discussion within the sector. Its design is therefore crucial. At the same time, there is a risk involved: if you include too much, you will no longer be able to see the wood for the trees.
The solution is a layered approach, similar to the concept behind ‘Pension 1-2-3’:
- Layer 1 — information that is always relevant to you as a director, supplemented by what currently requires attention.
- Layer 2 — in-depth information at the level of pension committees or similar bodies, depending on your governance structure.
- Layer 3 — the remaining relevant information, particularly important for the executive office in its role as guardian of operational management.
There is a particular point to note here. Monitoring reports typically focus on the present and the (recent) past. However, the mandate under the Wtp is partly formulated in prospective terms: a replacement value at retirement per age cohort. This makes the reporting scenario-driven and introduces model risk.
In practical terms, this means that monitoring must make the two key objectives measurable: for inflation risk, via an explicit KPI for inflation-tracking capacity per cohort (for example, the probability of an increase ≥ price inflation); and for choice options, via indicators showing whether participants can actually make appropriate choices — both before and after retirement. Only then can you measure whether you are on track to fulfil your mandate, rather than merely assessing your current position.
However, this does not yet determine what happens when the outcomes fall short of the target. You should therefore not only specify what you measure, but also which alert thresholds apply, what information is required if these are exceeded, who is responsible for analysis and follow-up, and when the matter is escalated to the board. Also make explicit which courses of action are available within the mandate, for example, adjustments to implementation, communication, investment policy or — where appropriate — policy principles for future decision-making.
A monitoring system that is useful for management purposes therefore answers at least four questions:
- Which outcomes do we track for each cohort and life stage?
- On the basis of which economic and stress scenarios do we assess those outcomes?
- When is an outcome so anomalous that further analysis, escalation or intervention is required?
- Which party does what, and what interventions are possible when actual performance consistently falls short of the target?
I set out in detail how to organise this scenario-driven monitoring in practice — from KPIs per cohort to independent model validation — in my article[1] on scenario analysis as a management tool. Furthermore, the choice of the scenario set itself is a control issue: also of interest in this context is the article[2] by my colleague Tarik Nbigui on the use of proprietary economic scenario sets and stress scenarios, which demonstrates how heavily the outcome — and thus your assessment of inflation resilience — depends on that choice of scenario.
Model risk, in this context, requires more than simply establishing a KPI. It calls for appropriate model governance: transparency regarding assumptions and limitations, periodic independent validation, assessment of relevant outcome sensitivities, and sufficient management understanding of the key drivers of the outcomes.
It is impossible to say with certainty in advance whether a scheme will keep fully pace with price inflation. It is the outcome of an interplay between interest rates, investment returns and inflation that can only be explored on a scenario-by-scenario basis. The management question is therefore not whether inflation is tracked exactly, but to what extent — and in which scenarios — your scheme adequately preserves purchasing power. It is precisely during the average twenty-year benefit payment phase that making this measurable and accounting for it is essential. That is exactly what scenario analysis is for.
The value of scenario analysis lies not only in reporting on possible outcomes, but also in the management discussion regarding their consequences. Which adverse outcomes are still in line with the risk appetite and objectives? When is further action required? And which actions are actually effective and feasible?
In short, the primary focus of first-line risk management lies in recalibrating the monitoring process. At its core is a closed management cycle: translating objectives into measurable indicators, assessing outcomes, following up on deviations, making adjustments where necessary, and then determining whether those adjustments have had an effect. The second-line risk manager, as the guardian of the framework, serves as a valuable sounding board in this process.
Where do you start?
Don’t try to do everything at once. At your next board meeting, ask one question: does our dashboard actually measure whether we are on track to fulfil our mandate, or does it merely show where we stand at present? Then ask the follow-up question: do we know in advance what we will do if that dashboard shows we are falling behind? The answer determines where your risk management begins.
You can read about the practical implementation of this first approach — scenario analysis, KPIs per cohort and management wargaming — in Tarik’s article and in my own article on scenario analysis (see footnotes) as a steering tool. In a forthcoming article, I will take you through the second approach: not optimising within the existing frameworks, but expanding the opportunities that the system can actually offer participants.
This article has been written in a personal capacity and reflects the author’s views. It does not necessarily represent the position of Milliman and should not be construed or cited as such.
[1] Risk management and scenario analysis as a steering tool: agile governance in uncertain times
[2] The importance of using proprietary economic scenario sets and stress scenarios in pension funds’ ALM calculations
Share this post!
Related posts
-
 Read more about "Dick Kamp & Bjorn Blom: Data quality as a foundation of reputation"
Dick Kamp & Bjorn Blom: Data quality as a foundation of reputation
-
 Read more about "DNB: Pensioentransitie en dekkingsgraad pensioenfondsen 1e kwartaal"
DNB: Pensioentransitie en dekkingsgraad pensioenfondsen 1e kwartaal
-
 Read more about "Dick Kamp: The Wtp requires a more differentiated and transparent approach to risk management"
Dick Kamp: The Wtp requires a more differentiated and transparent approach to risk management
-
Read more about "Dick Kamp: Risk management and the end-of-history illusion"
Dick Kamp: Risk management and the end-of-history illusion
-
Read more about "Dick Kamp: After the transition, optimisation begins"
Dick Kamp: After the transition, optimisation begins
-
 Read more about "Aon: Stijging dekkingsgraden pensioenfondsen houdt aan"
Aon: Stijging dekkingsgraden pensioenfondsen houdt aan
-
 Read more about "Amba Zeggen: Practice breeds resilience"
Amba Zeggen: Practice breeds resilience
-
 Read more about "Aon: Dalende rente zorgt voor daling dekkingsgraden pensioenfondsen"
Aon: Dalende rente zorgt voor daling dekkingsgraden pensioenfondsen
-
 Read more about "DNB: Transitie en dekkingsgraad pensioenfondsen 3e kwartaal 2026"
DNB: Transitie en dekkingsgraad pensioenfondsen 3e kwartaal 2026
-
 Read more about "Marsh: Nederland blijft wereldwijd koploper ondanks pensioenhervorming"
Marsh: Nederland blijft wereldwijd koploper ondanks pensioenhervorming