
Roundtable 'Social bonds'
Roundtable 'Social bonds'
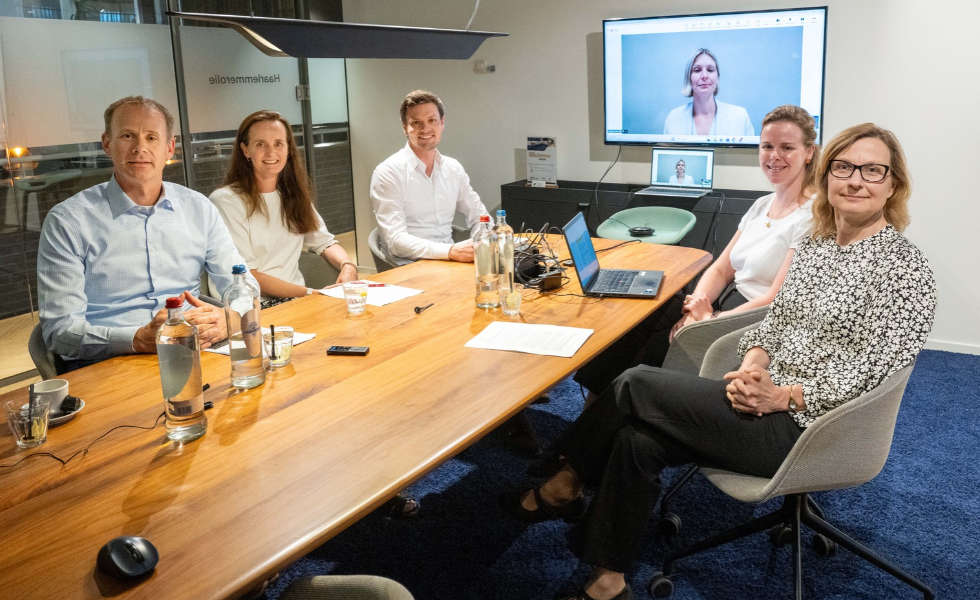
This report was originally written in Dutch. This is an English translation.
During the COVID-19 pandemic, social bonds were mainly used for employment programmes and to support small and medium-sized enterprises and the healthcare sector. Now, they are increasingly being used to tackle structural social inequalities. Social and green objectives are increasingly converging.
By Hans Amesz
|
CHAIR: Petra Stassen, AF Advisors
PARTICIPANTS: Bram Bos, Goldman Sachs Asset Management Gwennaële Bruning, Achmea Investment Management Letty Byatt, Columbia Threadneedle Investments Quintin Veldmeijer, PGGM Jessica Zarzycki, Nuveen |
How has the social bonds market developed since its early years?
Letty Byatt: ‘The real breakthrough for social bonds came during the COVID-19 pandemic. In 2020 and 2021, a huge amount of emergency funding was raised for social purposes, particularly through the European SURE programme (Support to mitigate Unemployment Risks in an Emergency). At the time, this represented around 98 billion euros and accounted for more than 30 per cent of the total market for rated bonds. Following the pandemic, that emergency funding declined. Since then, we have seen a more stable and mature market emerge. Whereas social bonds were primarily used during the pandemic for employment programmes, income support, and assistance for small and medium-sized enterprises and the healthcare sector, they are now increasingly being deployed to tackle structural social inequalities.’
Jessica Zarzycki: ‘Affordable housing has remained one of the most dominant themes within the social bond market. This is not surprising, as affordable housing is relatively easy to measure compared with many other social outcomes. Moreover, there is broad support for this theme amongst governments, local authorities, businesses and financial institutions. With other social themes, such as vocational training, healthcare or access to essential services, it is often more difficult to measure impact.’
Bram Bos: ‘If you look at the issuance figures for the past ten years, it is clear that the COVID-19 period has given a massive boost to the social bond market. Around 2020, growth expectations for this market were high. On a positive note, the segment has developed well since then. However, there are also areas for concern. For example, we had expected far more issuances from industrial companies investing in better working conditions or social provisions within their supply chains.’
Quintin Veldmeijer: ‘Whilst the number of social bonds within the overall market for sustainable bonds has fallen slightly, we are simultaneously seeing strong growth in sustainability bonds, which combine social and green objectives. Although green projects still dominate this segment, the social component is on the rise.’
What are the key factors behind the emergence and growth of the social bond market?
Gwennaële Bruning: ‘As far as corporate issuances are concerned, it is not only banks that are active. Property companies are also playing an increasingly significant role. Although the number of corporate issuances has increased, this segment of the market may have grown more slowly than some market participants had anticipated. At the same time, it is not surprising that the market for social bonds is still dominated by government-affiliated institutions. After all, many social objectives – such as affordable housing, social services or inclusion programmes – align more closely with public rather than corporate objectives.’
Zarzycki: ‘In recent years, the broader sustainability market has focused heavily on climate change and the energy transition. As a result, social issues have sometimes taken a back seat. For many people, however, social challenges are more urgent than climate issues. When someone lacks affordable housing, struggles to put food on the table or has no access to healthcare, those problems naturally take priority. As more capital is channelled into tackling social problems, this ultimately creates a more solid foundation for addressing long-term challenges, such as climate change.’
Byatt: ‘We are also seeing the reverse trend: some green investments inherently have a strong social component. Climate adaptation bonds are a good example. These involve, for instance, increasing the resilience of utilities, roads and other critical infrastructure, so that people retain access to drinking water, healthcare, transport and communications during natural disasters.’
What developments have you observed in the use of social bonds?
Veldmeijer: ‘Compared with five years ago, financial inclusion has become much more sophisticated. Initially, the emphasis was mainly on microfinance, but the market has now become much more targeted. There is an increasing focus on specific target groups, such as disadvantaged communities, minorities and women. As a result, the market has shifted from broad microfinance programmes to much more specifically defined social objectives.’
Bos: ‘We are seeing interest from some investors in sustainable and social investments in emerging markets. We see this with green bonds from emerging markets, but I think the same applies to social bonds. Some investors are considering investing in emerging markets via social bonds. This is particularly true now that many investors want to maintain exposure to US dollars, whilst at the same time seeking to broaden their geographical diversification.
Bruning: ‘We’re actually seeing a different trend. Many clients are looking for impact that’s visible closer to home. As a result, the focus is shifting towards the Netherlands and Europe rather than distant markets.’
Veldmeijer: ‘From the perspective of social impact, one could argue that it is precisely in emerging markets where the greatest differences can be made. Impact is also possible in developed markets, but the potential social added value is often considerably greater in emerging economies.’
Byatt: ‘It is true that the disparities between rich and poor countries are vast and that emerging markets offer many opportunities for impact. At the same time, you can also achieve substantial social outcomes in developed economies by focusing on vulnerable or disadvantaged groups. As part of our global strategy, we are keen to invest in emerging markets, but within our European and UK funds, we specifically seek out bonds that are strongly focused on those regions, with particular attention to vulnerable communities.’
One of the categories within social bonds is job creation. But how do you determine when job creation actually serves a social purpose rather than simply an economic one?
Bos: ‘Every organisation has its own definition of what is social, sustainable or impactful. For example, we look specifically at financing for small and medium-sized enterprises in regions with above-average unemployment. At the same time, this illustrates precisely why social bonds are complex. What is socially relevant in one region may not be so elsewhere. Consequently, the analysis requires far more bespoke work than is the case with green projects. With a wind farm, it is relatively straightforward to determine the environmental impact, regardless of where it is located. With social housing or employment programmes, the situation is much more nuanced. That is why each party has ultimately developed its own assessment framework.’
For many people, social challenges are more urgent than climate issues.
Zarzycki: ‘I think new social issues are emerging around developments such as artificial intelligence and data centres. When we engage with major technology companies, we discuss not only their environmental impact, but also their relationship with local communities, investments in education and vocational training, and their broader social responsibility.’
Have any new sectors or regions emerged in recent months or years?
Zarzycki: ‘We are seeing particularly strong growth in the field of blended finance. Good examples include the so-called Orange Bonds and the series of Women’s Livelihood Bonds. These instruments make it possible to channel capital into regions where investment is traditionally more difficult, whilst at the same time making a specific contribution to economic opportunities for women. Globally, women still receive only a very small proportion of the available funding. The economic potential of improved access to capital is therefore enormous.’
Bruning: ‘When it comes to social bonds, we must be wary of having too many different labels, frameworks and classifications. The more fragmentation there is, the harder it becomes to channel capital efficiently towards social and green projects.’
Byatt: ‘Thematic bonds are on the rise. For example, we are seeing bonds specifically focused on healthcare, gender equality or affordable housing. These instruments are valuable to investors because they define much more clearly which projects are being financed. This makes impact analysis simpler than with broad social bonds that combine diverse categories.’
Bos: ‘In recent years, we have seen increasingly specific forms of “use of proceeds” bonds. These are bonds where the proceeds are earmarked in advance for specific projects or expenditure. We recently saw an interesting example of a bond focused on the consequences of glacier melt. The proceeds are used to help communities adapt to the effects of climate change.
What developments are you seeing in the field of impact measurement and reporting?
Bos: ‘The situation has certainly improved in recent years. At the same time, the underlying methodologies still vary widely. As a result, consolidating impact data within a social bond fund remains a major challenge. I also believe that reporting KPIs alone is not enough. Quantitative data tells only part of the story. Case studies can help to better understand social outcomes in practice. I see engagement as one of the most powerful elements of the ‘use of proceeds’ model.’
Zarzycki: ‘It is no longer solely about green impact, but also about questions regarding the benefit to the community and issues such as: which communities benefit from this, what health benefits arise, and what broader societal impacts are achieved? We expect this form of reporting to become even more important in the future.
When it comes to social bonds, we must be careful not to have too many different labels, frameworks and classifications.
Byatt: ‘We are very positive about the emergence of social co-benefits within green bonds. We use case studies to give clients a real insight into what their investment has made possible.’
Bruning: ‘If we place too much emphasis on increasingly extensive quantitative reporting, we run the risk of overestimating the impact or creating unnecessary complexity. We must avoid raising the bar for issuing social bonds ever higher. After all, additional reporting requirements entail costs and administrative burdens. Although AI may be able to alleviate some of these burdens in the future, it remains important to maintain a good balance between information needs and practicality.’
What obstacles do investors face when considering allocating a specific portion of their portfolio to social bonds? And how can these obstacles be overcome?
Byatt: ‘The market for social bonds is still relatively concentrated. Governments, supranational institutions and development banks dominate the issuance volume. The number of corporate issuances therefore remains limited. This is logical, as many social projects align more closely with public policy objectives than with the core activities of companies. This can be resolved by approaching social bonds from a broader perspective, looking at social outcomes across all designated labelled bonds and possibly even at the ‘general corporate purpose’ of highly socially oriented entities, such as charitable organisations.’
Bos: ‘The debate surrounding green and social bonds often centres on a few basis points’ difference in yield compared with traditional bonds. That discussion may be given too much attention, as the potential difference is currently very limited and often barely measurable. As far as we are concerned, the far more important question is what the inclusion of green or social bonds means for the portfolio as a whole. Does it alter the risk diversification? Which issuers are you adding? How does that affect the overall portfolio structure? Moreover, we sometimes see that issuers who previously issued only conventional bonds are assessed differently by the market following their first green or social issue. That effect can extend across their entire yield curve. Such broader market effects are likely more important than the question of whether a limited ‘greenium’ is present on a specific bond.’
Veldmeijer: ‘I think a greenium mainly arises when there is scarcity. We saw that with the first generation of green bonds. At that time, supply was limited and demand was high. This led to a temporary price differential. As the market grew and more issues became available, that effect largely disappeared.
How do social bonds find a place in the portfolio? And what, if anything, might be holding investors back from investing in them?
Bos: ‘The key question is not whether you invest in social bonds as a standalone asset class, but what the impact is on your overall portfolio. When you look at the global bond market, exposure is often concentrated among a limited number of large issuers. By adding impact bonds, that concentration can shift. For example – depending on the overall portfolio – you may reduce the weighting of dominant issuers and create the potential for greater diversification within the portfolio.’
Bruning: ‘Due to the limited diversification within the social bond universe, I expect allocations to social bonds to always be smaller than those to green bonds. In my view, it would not be prudent to replace a large portion of a fixed-income portfolio exclusively with social bonds.
The far more important question is what the addition of green and social bonds means for the portfolio as a whole.
Zarzycki: ‘Including both green and social bonds creates greater flexibility and better diversification within the portfolio. If you focus exclusively on a single theme, there is a risk of over-concentration. By taking a broader view, you can manage the portfolio in a more traditional fixed-income manner, whilst at the same time pursuing positive environmental and social outcomes.’
Byatt: ‘Our clients are indeed increasingly seeking an integrated approach to social and environmental issues. The reason for this is simple: social and environmental problems are not separate from one another. Within our funds, every bond must first meet all the exclusion criteria. We then carry out an in-depth analysis of the positive social outcomes. In doing so, we look at themes such as affordable housing, healthcare, education, employment and resilient essential services that contribute to a sustainable society.’
Investing in private markets is becoming increasingly popular, particularly when positioned as impact investing. Does this trend come at the expense of social bond funds and social mandates, or do the two actually reinforce one another?
Bruning: ‘We are indeed seeing growing interest in private credit and private equity within impact investing. However, we do not perceive this as a shift away from labelled bonds. Both approaches are complementary. The type of investor may also play a role. Smaller or less experienced institutional investors are often more attracted to the market for labelled bonds because of its accessibility and transparency. More experienced investors are more frequently active in private markets. On balance, we do not see a substitution effect between the two segments.’
Veldmeijer: ‘Both markets can co-exist perfectly well. If you define impact very strictly and place great emphasis on additionality, then the private market may seem attractive. There, it is often easier to demonstrate a direct contribution to a project or enterprise. However, if you apply a broader definition of impact, social bonds can be just as suitable an instrument.
Zarzycki: ‘What is unique to the fixed-income market is the role of governments. Through government bonds, municipal bonds and issues by multilateral development banks, investors can contribute directly to social objectives on a large scale. That is precisely why public markets remain a powerful instrument for social impact.’
Bos: ‘I agree that both markets can go hand in hand. Our experience is that when investors choose to dedicate part of their portfolio to impact investing, they usually do so across multiple asset classes. Labelled bonds are often a logical first step, as virtually every institutional investor already has a substantial allocation to liquid bonds. In addition, we see, for example, that pension funds invest in private impact funds, whilst using social or green bonds as part of their liquidity management. This precisely demonstrates how both approaches can complement each other.
Have you noticed that clients wishing to invest in social bonds are becoming increasingly well-informed and have more explicit views on impact?
Byatt: ‘Over the past few years, clients have developed a much more positive view of impact investing. Discussions have become more substantive, and investors are asking increasingly targeted questions about the actual social outcomes of their investments.’
Are there any themes that you expect social bonds to address more effectively in the future?
Bruning: ‘We are seeing a shift from a relatively narrow focus on climate transition towards a broader approach that also centres on a just transition and social outcomes. In addition, interest in biodiversity is growing. Whilst this is not exclusively relevant to social bonds, the broadening of the sustainability agenda does present opportunities for this market.’
Veldmeijer: ‘Biodiversity does indeed offer opportunities. Furthermore, themes such as food security, health and sustainable food production are becoming increasingly intertwined. These topics are often associated with green bonds, but at the same time have a social dimension. These themes will play a greater role within the social bond market in the future.’
Bos: ‘The impact of AI on employment could become a point of discussion in the social bond market in the future, but it is not yet widely reflected in the frameworks. AI can lead to higher productivity and lower costs for businesses, but at the same time raises questions about the future of jobs and labour markets. How do we ensure that the economic benefits of AI do not come at the expense of employment or social cohesion? I expect we will see this topic featured more frequently in the documentation of social bonds in the coming years.’
Byatt: ‘AI is both an opportunity and a risk. Differences are already emerging between groups that do and do not have access to advanced AI solutions. Consider, for example, differences between students from affluent and less affluent families, or between different demographic groups. This creates the risk that existing inequalities will widen further. At the same time, this presents opportunities for social bonds. Technology companies could, for example, issue bonds specifically aimed at reducing digital inequality and promoting equal access to AI technology.
Zarzycki: ‘There is increasing transparency among multilateral development banks and supranational institutions. One example is the Inter-American Development Bank, which has issued a so-called Amazonia bond. In addition to the bond itself, the institution also publishes guidelines that can be used by other banks and investors. The bond specifically targets communities in the Amazon region and funds, amongst other things, vocational training, economic development and sustainable forestry. We see the same approach at institutions such as the CAF, the Development Bank of Latin America and the Caribbean – originally known as the Corporación Andina de Fomento – which have issued bonds focused on children, young people, education and social development. By reporting transparently and drawing up clear guidelines, these kinds of institutions raise the standard for the entire market. This ultimately contributes to better impact measurement and stronger reporting.’
How can green and social bonds actually reinforce each other, and how can a combined approach lead to more tangible impact?
Zarzycki: ‘Green and social objectives are increasingly converging. Take a renewable energy project in an emerging market, for example. This is not just about the energy transition, but also about issues such as access to energy, employment, education and economic development. The same applies to drinking water projects. The environmental benefits are important, but the social benefits are at least as relevant. Our experience is that projects are more successful when this social component is explicitly taken into account. I therefore expect the market to continue to evolve towards integrated solutions in which social and green objectives reinforce one another.’
Projects that have both a green and a social component could become a key driver of growth in the future.
Five to seven years ago, the emphasis was mainly on achieving environmental objectives, whilst trying to prevent social harm. Is the focus now shifting towards actively creating a positive impact in both areas?
Bos: ‘I think so. As investors, we have an important role to play vis-à-vis issuers. We must make it clear that transparency, reporting and a clear description of social impacts are important for the market. If issuers of green bonds also provide insight into the social benefits their projects deliver, this could lead to a broader investor base and potentially more favourable financing terms. That is why engagement remains crucial. Through dialogue with issuers, we can contribute to further improving the market and to better integration of social and green bonds.
Can the issuance of social bonds by governments actually help to stimulate or accelerate social investment? Might a social bond framework force organisations to adopt greater discipline, set more precise targets and allocate resources in a more targeted manner, given that the proceeds must be specifically earmarked and the impact measured?
Bos: ‘This remains partly a chicken-and-egg question. Ultimately, transparency is the greatest strength of the “use of proceeds” model. The question of whether issuing a social bond in itself stimulates additional investment is more difficult to answer, but I do see many positive side effects. For instance, it raises awareness within organisations. People start to think more explicitly about social and sustainable spending. Furthermore, we see – particularly in emerging markets – that governments and companies which are the first to issue social bonds often set an example.’
Bruning: ‘Additionality is always a somewhat trickier concept when it comes to public expenditure, as the expenditure in question was often already planned. Nevertheless, a social bond framework ensures that issuers must define their target group, apply clear categories and report on the impact achieved. This significantly improves the quality of the information provided, which is extremely valuable to the market.’
How do you view the future of the social bond market?
Bos: ‘I’ve been pleasantly surprised by developments in Europe. Several new issuers have entered the market this year, whilst many thought that virtually all potential European issuers were already active. I also expect further growth in social bond issuance in emerging markets.’
Byatt: ‘Where I see a great deal of potential is in the combination of climate adaptation and social impact. It is precisely projects that have both a green and a social component that could become a key driver of growth in the future.’
What are your expectations for the social bond market following the introduction of a potential EU taxonomy for social criteria?
Veldmeijer: ‘Just as the European standard for green bonds provides a framework of reference, a social taxonomy could serve as a kind of quality standard. At the same time, independent analysis will always remain necessary.
Bos: ‘I expect it will be difficult to define universally what constitutes a social objective, as standards and priorities vary greatly between countries and societies.
If you define impact very strictly and place great emphasis on additionality, then the private market may seem attractive.
Bruning: ‘An EU taxonomy is, in itself, a useful tool for creating greater standardisation and transparency. At the same time, many social issues fall primarily within the remit of Member States. So, politically speaking, this is a tricky subject and I see little chance of an official EU taxonomy being introduced in the short or medium term.’
Do you see any new opportunities for social bonds that currently fall outside the standard categories of the ICMA framework?
Bruning: ‘I don’t see any urgent need for entirely new categories. Rather, I expect the market to develop further towards increasingly specific themes within the existing categories.’
Byatt: ‘In general, I find the current ICMA framework broad enough to address most forms of social inequality and social challenges.’
Zarzycki: ‘I see opportunities primarily in new applications of existing frameworks. Take, for example, the reconstruction of areas affected by conflict. Should a sustainable peace agreement be reached in Ukraine or in parts of the Middle East, for instance, this could lead to significant demand for social financing for reconstruction, education, employment and social development. In addition, we are seeing an interesting development around so-called debt-for-nature swaps. It is conceivable that similar structures could emerge for issues such as food security or education, whereby funds are made available at national level for specific social objectives.’
|
SUMMARY The COVID-19 pandemic has given the social bond market a significant boost. The social bond market is still dominated by government-related objectives, as many social objectives align more closely with public rather than corporate objectives. There is an increasing focus on specific target groups, such as disadvantaged communities, minorities and women. A key question when investing in social bonds – and indeed in green bonds – is what impact this has on the overall portfolio. Including both creates greater flexibility and better diversification within the portfolio. The impact of AI on employment could become a topic of discussion in the social bond market in the future. |
|
Petra Stassen Petra Stassen is Head of Sustainability at AF Advisors. She joined the Ministry of Finance’s Agency in 2003 and subsequently worked at NN Investment Partners and its legal successor, Goldman Sachs Asset Management. For the past 10 years, her focus has been on sustainable investment. At AF Advisors, she is further expanding the range of services and advice relating to sustainable investment. |
|
Bram Bos Bram Bos is Managing Director at Goldman Sachs Asset Management and serves as Global Head of Sustainable and Impact Fixed Income. He leads a team that focuses primarily on managing portfolios allocated 100 per cent to ‘labelled bonds’. Bos has 25 years’ experience in portfolio management. |
|
Gwennaële Bruning Gwennaële Bruning has been Head of Credits at Achmea Investment Management since 2014. Under her leadership, various credit- and impact-focused mandate strategies and fund solutions have been developed. Previously, she worked at Achmea Group, where she was responsible for the fixed-income portfolios of the insurer, AXA Investment Managers and NN Investment Partners. Bruning studied Economics at the University of Amsterdam. |
|
Letty Byatt Letty Byatt has been a Social Impact Analyst in the Investment Grade Credit team at Columbia Threadneedle Investments since 2022. She works with portfolio managers on social impact opportunities within social bond strategies and previously held the role of Client Manager at Royal London Asset Management. She holds a certificate in ESG Investing from the CFA Institute and has completed a course in Sustainable Finance at the University of Cambridge. |
|
Quintin Veldmeijer Quintin Veldmeijer has been working at PGGM as a Credit Analyst and Portfolio Manager since 2019. In this role, he is responsible for the automotive and capital goods sectors and is also a specialist in the field of ESG. The PGGM credit team manages the Global Credit and Euro Investment Grade Credit mandates for PFZW. Veldmeijer studied Finance at Tilburg University. |
|
Jessica Zarzycki Jessica Zarzycki is a Portfolio Manager within Nuveen’s global fixed income team, specialising in ESG and impact strategies. She is Lead Portfolio Manager for the Global Core Impact strategy and Co-Portfolio Manager for several ESG/impact bond strategies. Zarzycki began her career at Nuveen in 2008 and holds a Bachelor’s degree in Business Administration from The Ohio State University. |
Read the report in the digital magazine