
L&G: Why euro credit is becoming a global opportunity
A deeper, more global euro credit market is creating potential opportunities for investors seeking to diversify dollar-heavy portfolios. Capturing them requires looking beyond headline spreads to sector composition, maturity and relative value.
By Ian Hutchinson, Marc Rovers, Lan Wu and Radha Mathur
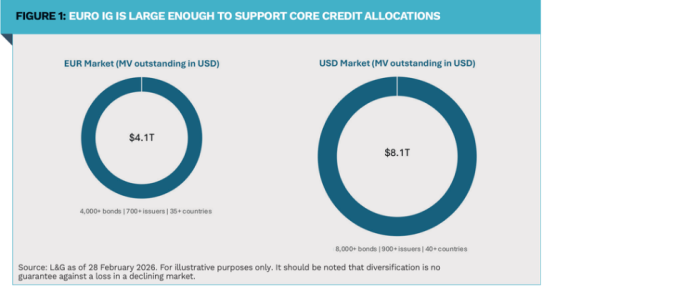
for diversification are looking beyond their traditional hunting grounds. As a result, there is a growing interest in the euro investment grade (IG) credit market, which has transformed over the past two decades. Europe’s corporate bond markets have grown substantially in scale and depth: euro-area non-financial companies alone have grown from € 977 billion in 2016 to € 1.76 trillion in April 2026.¹
Euro IG has grown into a large, diversified market
But size alone does not tell the full story. Over the years, the market has become deeper, more liquid and more diverse in its issuer base, while the maturity spectrum has expanded. Once predominantly a shorter dated market, euro credit is seeing greater issuance further along the yield curve, giving investors more flexibility to express duration and credit views.
That evolution is particularly relevant as global investors reconsider portfolios heavily exposed to US assets amid recent de-dollarisation trends. Some US and Asian pension funds and central-bank reserve managers are reassessing concentrated exposure to US equities, US duration and the US dollar. As they diversify incrementally, euro-denominated fixed income is one of the few liquid markets large enough to absorb meaningful allocations.
Yield is back, but selectivity matters
Valuations require nuance. Credit spreads remain historically tight versus government bonds, but this is against a backdrop of growing sovereign debt burdens. More attractive spreads, especially for the higher rated issues versus swaps, and all-in yields tell a different story. Euro IG credit currently offers yields above 3.5% with around four and-a-half years of duration² – levels that remain attractive relative to much of the post-global financial crisis period.
Demand has consequently remained resilient. A notable development in Europe has been the rapid expansion of target date funds, creating sustained investor appetite for three- to seven-year bonds. The shorter duration nature of the asset class may also appeal to global investors concerned about interest rate risk. Since the Covid-19 pandemic, euro IG credit has exhibited lower return volatility than government bond markets. That running yield combined with the limited duration may appeal to investors seeking income but remain wary of rate volatility.
Yet attractive yields should not be mistaken for universally attractive valuations. With spreads compressed and limited dispersion between issuers and ratings, the opportunity increasingly lies beneath the index level: identifying relative value between sectors, issuers, maturities and currencies. We believe this reinforces the importance of active credit selection, where security selection can uncover potential opportunities.
A different market from the US
We believe euro credit also offers something increasingly valuable in today’s environ ment: a different sector composition. Banks, utilities, telecoms and industrial companies remain substantial components of the market. Technology, by contrast, represents a much smaller portion of euro IG credit compared with the US. That matters, given the vast AI-related capital expenditure requirements reshaping global credit markets.
US hyperscalers have so far mostly funded themselves in dollars, often at longer maturities. For global investors, this raises questions not only about concentration but about the relationship between debt maturity and the economic life of rapidly evolving AI infrastructure.
We believe euro markets could increasingly provide an alternative funding source and have already seen hyperscaler issuance begin to move into euros. Strong demand, particularly at shorter maturities, may prove attractive to technology companies looking to diversify funding.
This creates both opportunity and risk. On the one hand, more hyperscaler issuance would broaden the euro market and give investors additional access to high-quality global companies. At the same time, it may increase issuer concentration, which is something currently seen in some parts of the US credit market. The distinction is that euro investors are starting from a much lower base. They can potentially participate selectively in this structural theme without assuming the same benchmark exposure.
Energy provides another point of difference. US credit has significantly greater exposure to energy producers, while euro benchmarks remain comparatively light, reflecting both Europe’s industrial structure and the greater prominence of ESG considerations among European investors
They simply create different sources of risk and return, meaning exposure to both within a global portfolio can offer potential diversification benefits and a broader opportunity set.
From regional allocation to global relative value
These differences become especially valuable when credit markets are viewed globally rather than as separate regional silos. This approach is key as the sources of opportunity change. During periods such as the European sovereign debt crisis or Covid-19, macro analysis assumed greater importance. In today’s environment of tight spreads, the emphasis has shifted towards bottom-up sector and issuer selection.
A global lens for euro credit
Investors outside Europe have historically allocated relatively little to the region’s fixed income landscape, reflecting familiarity with and the depth of US dollar markets. But interest is increasing among asset owners, such as within Asia, seeking to diversify their exposure. The geopolitical backdrop is part of that shift, but we believe the investment case goes further.
Euro credit is now sufficiently large, liquid and diversified to function as a meaningful player in global credit portfolios in its own right. Its shorter duration and different sector mix can complement dollar portfolios, while its expanding issuer base gives investors access to many of the same global companies through a different market structure.
Europe itself is also changing. Greater fiscal expansion, including increased defence and infrastructure expenditure, is creating a different growth and issuance environment from the austerity-focused period following the sovereign debt crisis. The question for allocators is not ‘should euro credit replace US credit?’, but ‘are portfolios built predominantly around dollar assets taking full advantage of the global opportunity set?’
The answer is not simply to own more regions. It is to understand how those markets differ, where relative value lies and how those differences can be combined. As euro credit comes of age, we believe such characteristics are making it an increasingly integral part of the global fixed income opportunity set.
Read the report in the digital magazine